Company Coverage
Kiatnakin Phatra Bank (KKP TB): 3Q26: Results Beat; A Positive Surprise From Non-II
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt114.50
Bt150.00
31.0%
Bt135.00
Analyst
Highlights
- KKP reported a net profit of Bt2.4b in 3Q26, up 43% yoy and 13% qoq.
- The wealth business drove non-II, and is one of KKP’s key earnings drivers.
- Maintain BUY with a higher target price of Bt150.00 (previously: Bt135.00).
Analysis
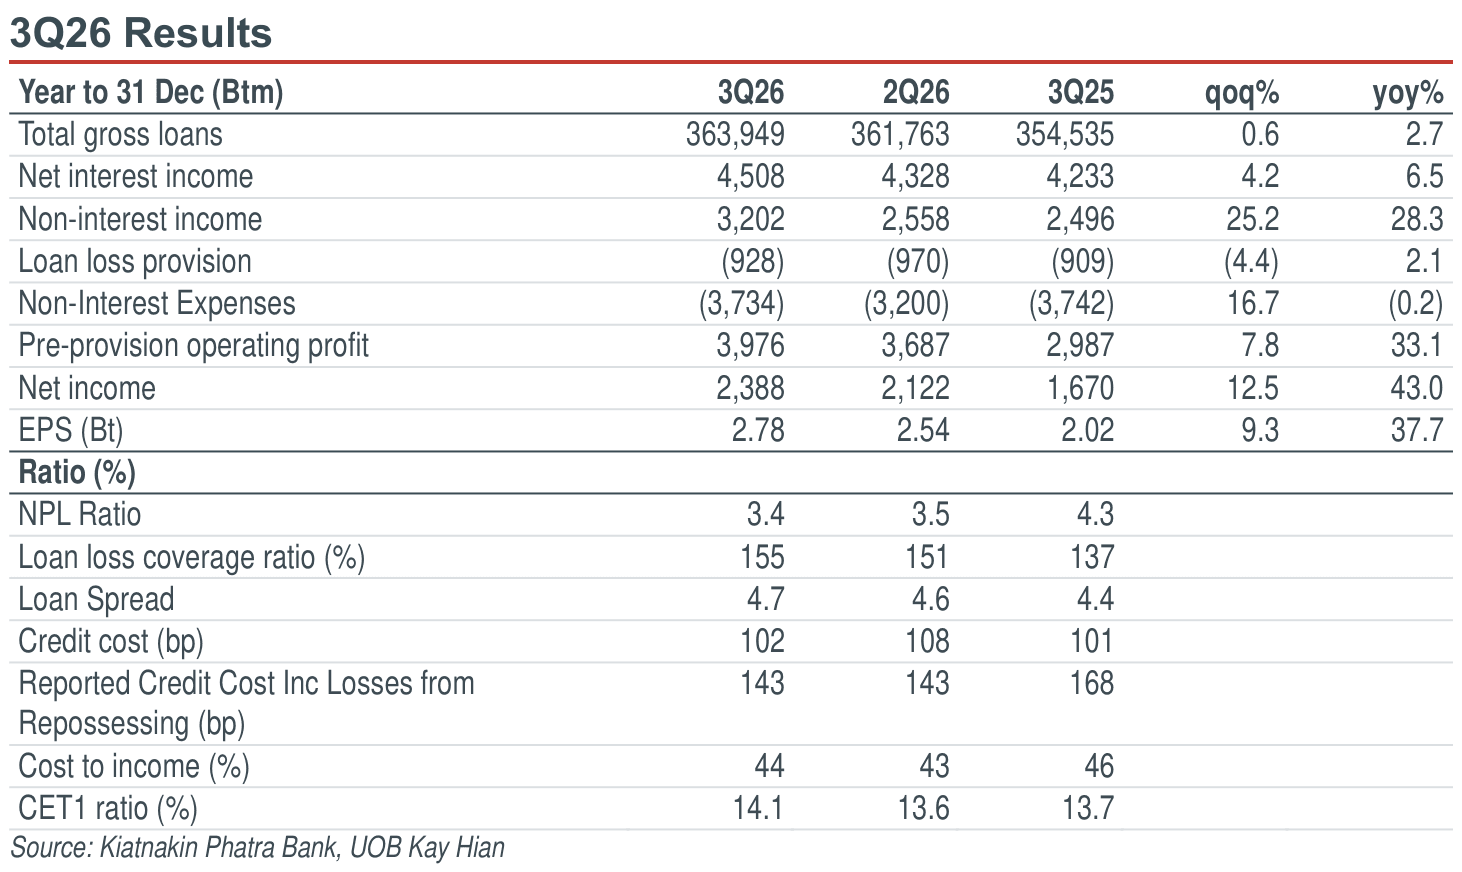
- 3Q26 results beat expectations. Kiatnakin Phatra Bank (KKP) reported a net profit of Bt2.4b for 3Q26, up 43% yoy and 13% qoq. The results beat our and consensus expectations by 24% and 15% respectively. The key positive surprise was non-II coming in 43% higher than our expectation, mainly attributable to: a) an impressive fee and service income, and b) the gain on financial instruments measured at fair value through profit or loss (FVPL) of Bt562m in 3Q26, which rose 98% qoq. Pre-provision operating profit jumped 33% yoy and 8% qoq.
- Loan portfolio grew qoq. In 3Q26, KKP reported loan outstanding of Bt363b, growing 3% yoy and 1% qoq. In 9M26, the loan portfolio grew 3.7% yoy (vs the bank’s target of 3% yoy for 2026).
Highlights
- KKP reported a net profit of Bt2.4b in 3Q26, up 43% yoy and 13% qoq.
- The wealth business drove non-II, and is one of KKP’s key earnings drivers.
- Maintain BUY with a higher target price of Bt150.00 (previously: Bt135.00).
Analysis
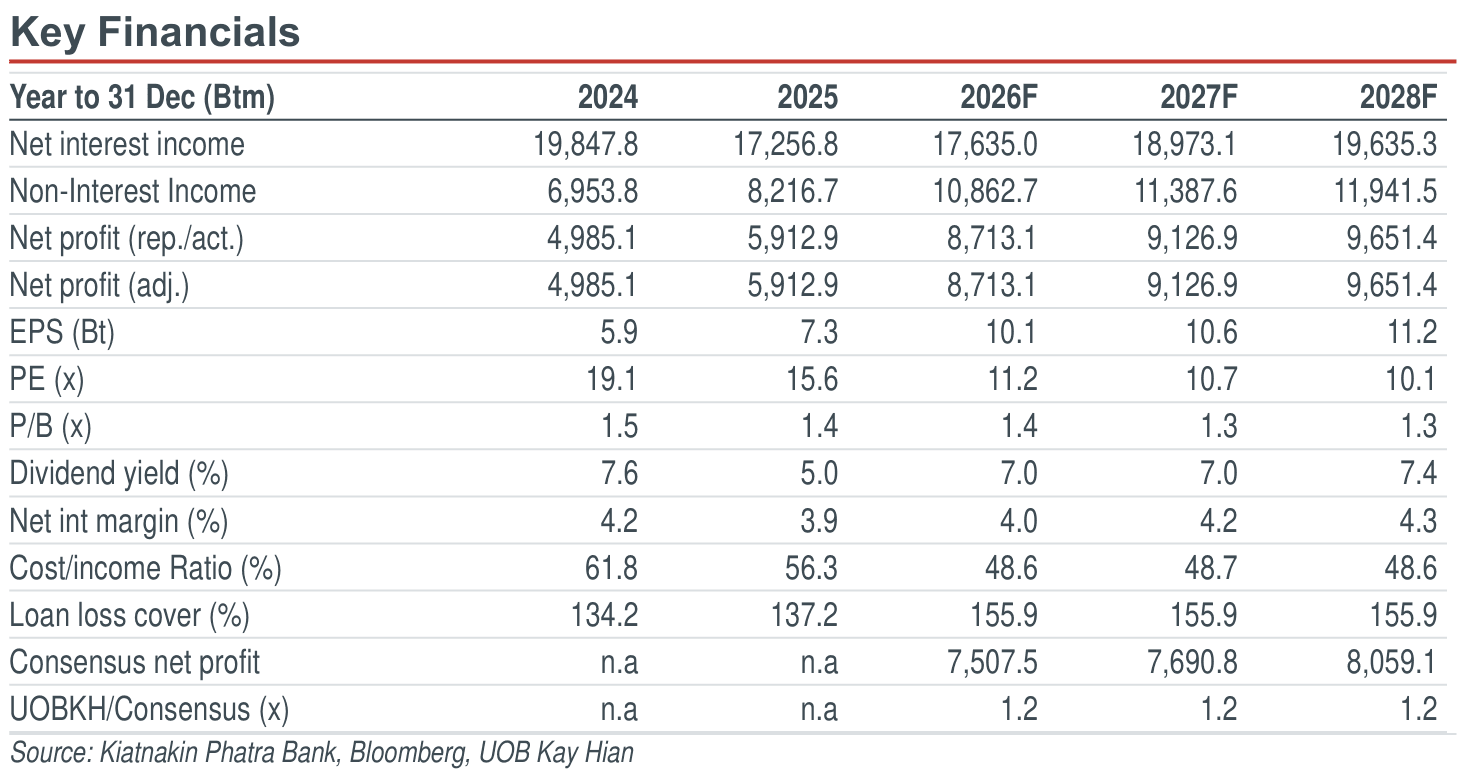
- 3Q26 results beat expectations. Kiatnakin Phatra Bank (KKP) reported a net profit of Bt2.4b for 3Q26, up 43% yoy and 13% qoq. The results beat our and consensus expectations by 24% and 15% respectively. The key positive surprise was non-II coming in 43% higher than our expectation, mainly attributable to: a) an impressive fee and service income, and b) the gain on financial instruments measured at fair value through profit or loss (FVPL) of Bt562m in 3Q26, which rose 98% qoq. Pre-provision operating profit jumped 33% yoy and 8% qoq.
- Loan portfolio grew qoq. In 3Q26, KKP reported loan outstanding of Bt363b, growing 3% yoy and 1% qoq. In 9M26, the loan portfolio grew 3.7% yoy (vs the bank’s target of 3% yoy for 2026).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt114.50
Bt150.00
31.0%
Bt135.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Oct 2026
Bangkok Bank (BBL TB): 3Q26: Results In Line With Consensus; Showing Clean Loan Portfolio

22 Oct 2026
SCB X (SCB TB): 3Q26: Results In Line With Consensus; Investment And Trading Income Are Loss Making

22 Oct 2026
Krung Thai Bank (KTB TB): 3Q26: Results In Line; Credit Costs Decline QOQ
Our latest research

22 Oct 2026
Betagro (BTG TB): 3Q26 Results Preview: Thai Livestock Producers Are Winners

22 Oct 2026
Kasikorn Bank (KBANK TB): 3Q26: Results In Line; Reiterate Achieving 2026 Credit Cost Target
22 Oct 2026