Company Coverage
SCB X (SCB TB): 3Q26: Results In Line With Consensus; Investment And Trading Income Are Loss Making
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt146.00
Bt180.00
23.3%
Bt190.00
Analyst
Highlights
- SCB reported a 3Q26 net profit of Bt10.7b (-11% yoy, -4% qoq).
- The company is in the process of cleaning up the AutoX loan portfolio.
- Maintain BUY with a lower target price of Bt180.00 (previously Bt190.00).
Analysis
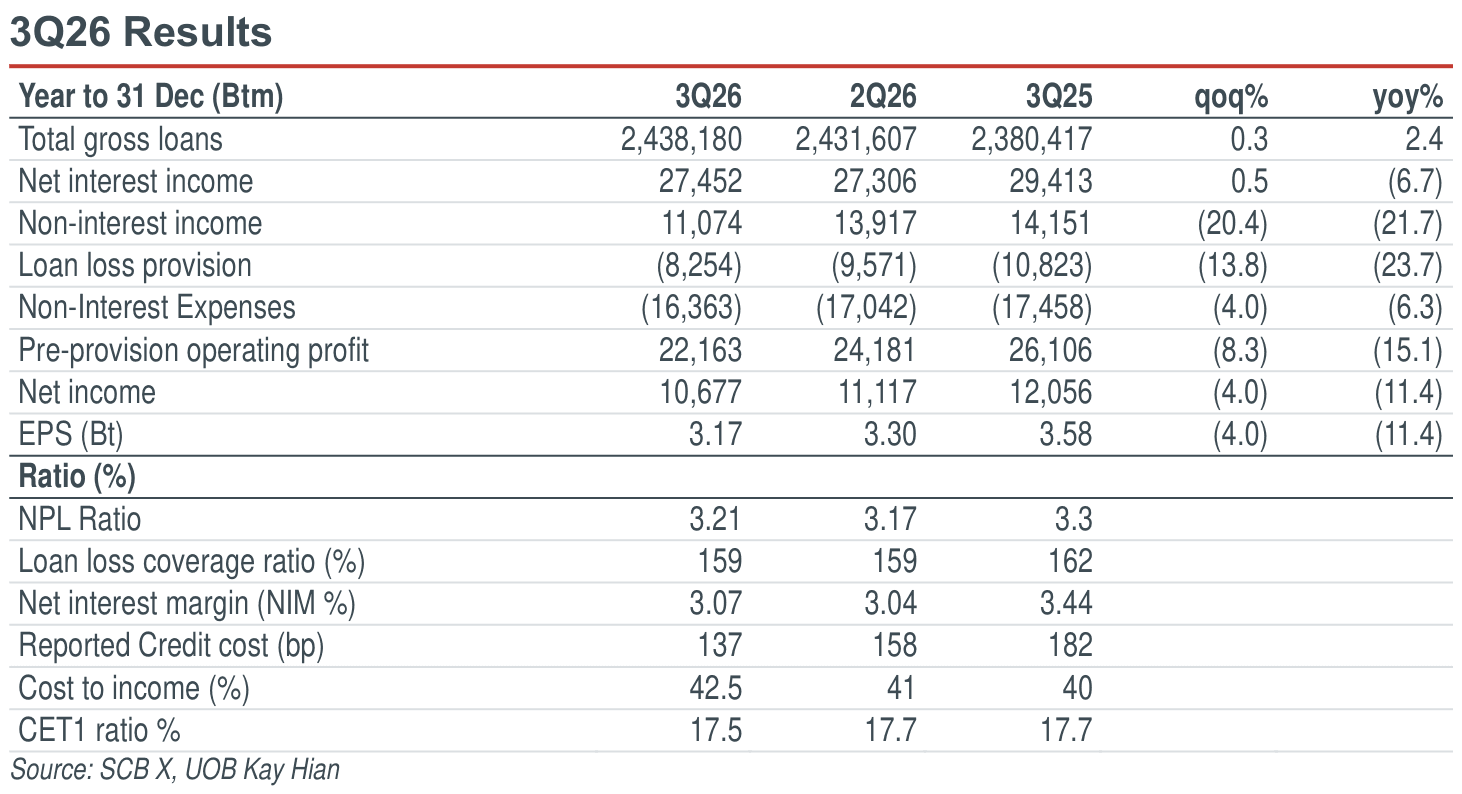
- 3Q26 results in line with consensus. SCB X (SCB) reported a 3Q26 net profit of Bt10.7b (-11% yoy, -4% qoq). The results were in line with consensus forecasts but below our expectation by 8% due to a lower-than-expected non-interest income (non-II). Pre-provision operating profit declined by 15% yoy and 8% qoq in 3Q26. Loan portfolio grew 2% yoy and flat qoq in 3Q26. In 9M26, loan portfolio grew 2.4% yoy.
- Neutral tone at analyst meeting. We attended SCB’s analyst meeting, and the tone was neutral. Management stated that the asset quality is well controlled though they need another next quarter to clean up the loan portfolio in the auto loan business. The prominent loan portfolio is driven by corporate loans (40% exposure to total loan portfolio). The corporate loan grew 12% yoy in 9M26 and showed healthy asset quality.
Highlights
- SCB reported a 3Q26 net profit of Bt10.7b (-11% yoy, -4% qoq).
- The company is in the process of cleaning up the AutoX loan portfolio.
- Maintain BUY with a lower target price of Bt180.00 (previously Bt190.00).
Analysis
- 3Q26 results in line with consensus. SCB X (SCB) reported a 3Q26 net profit of Bt10.7b (-11% yoy, -4% qoq). The results were in line with consensus forecasts but below our expectation by 8% due to a lower-than-expected non-interest income (non-II). Pre-provision operating profit declined by 15% yoy and 8% qoq in 3Q26. Loan portfolio grew 2% yoy and flat qoq in 3Q26. In 9M26, loan portfolio grew 2.4% yoy.
- Neutral tone at analyst meeting. We attended SCB’s analyst meeting, and the tone was neutral. Management stated that the asset quality is well controlled though they need another next quarter to clean up the loan portfolio in the auto loan business. The prominent loan portfolio is driven by corporate loans (40% exposure to total loan portfolio). The corporate loan grew 12% yoy in 9M26 and showed healthy asset quality.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt146.00
Bt180.00
23.3%
Bt190.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


